Your Tigard Oregon home insurance needs are shaped by factors most national insurers overlook. Rain, hail, and Oregon’s specific building codes create coverage gaps that generic policies simply don’t address.
At AOA West, Inc., we’ve spent years helping Tigard homeowners navigate these local complexities. The right protection starts with understanding your community’s real risks.
What Makes Tigard Home Insurance Different
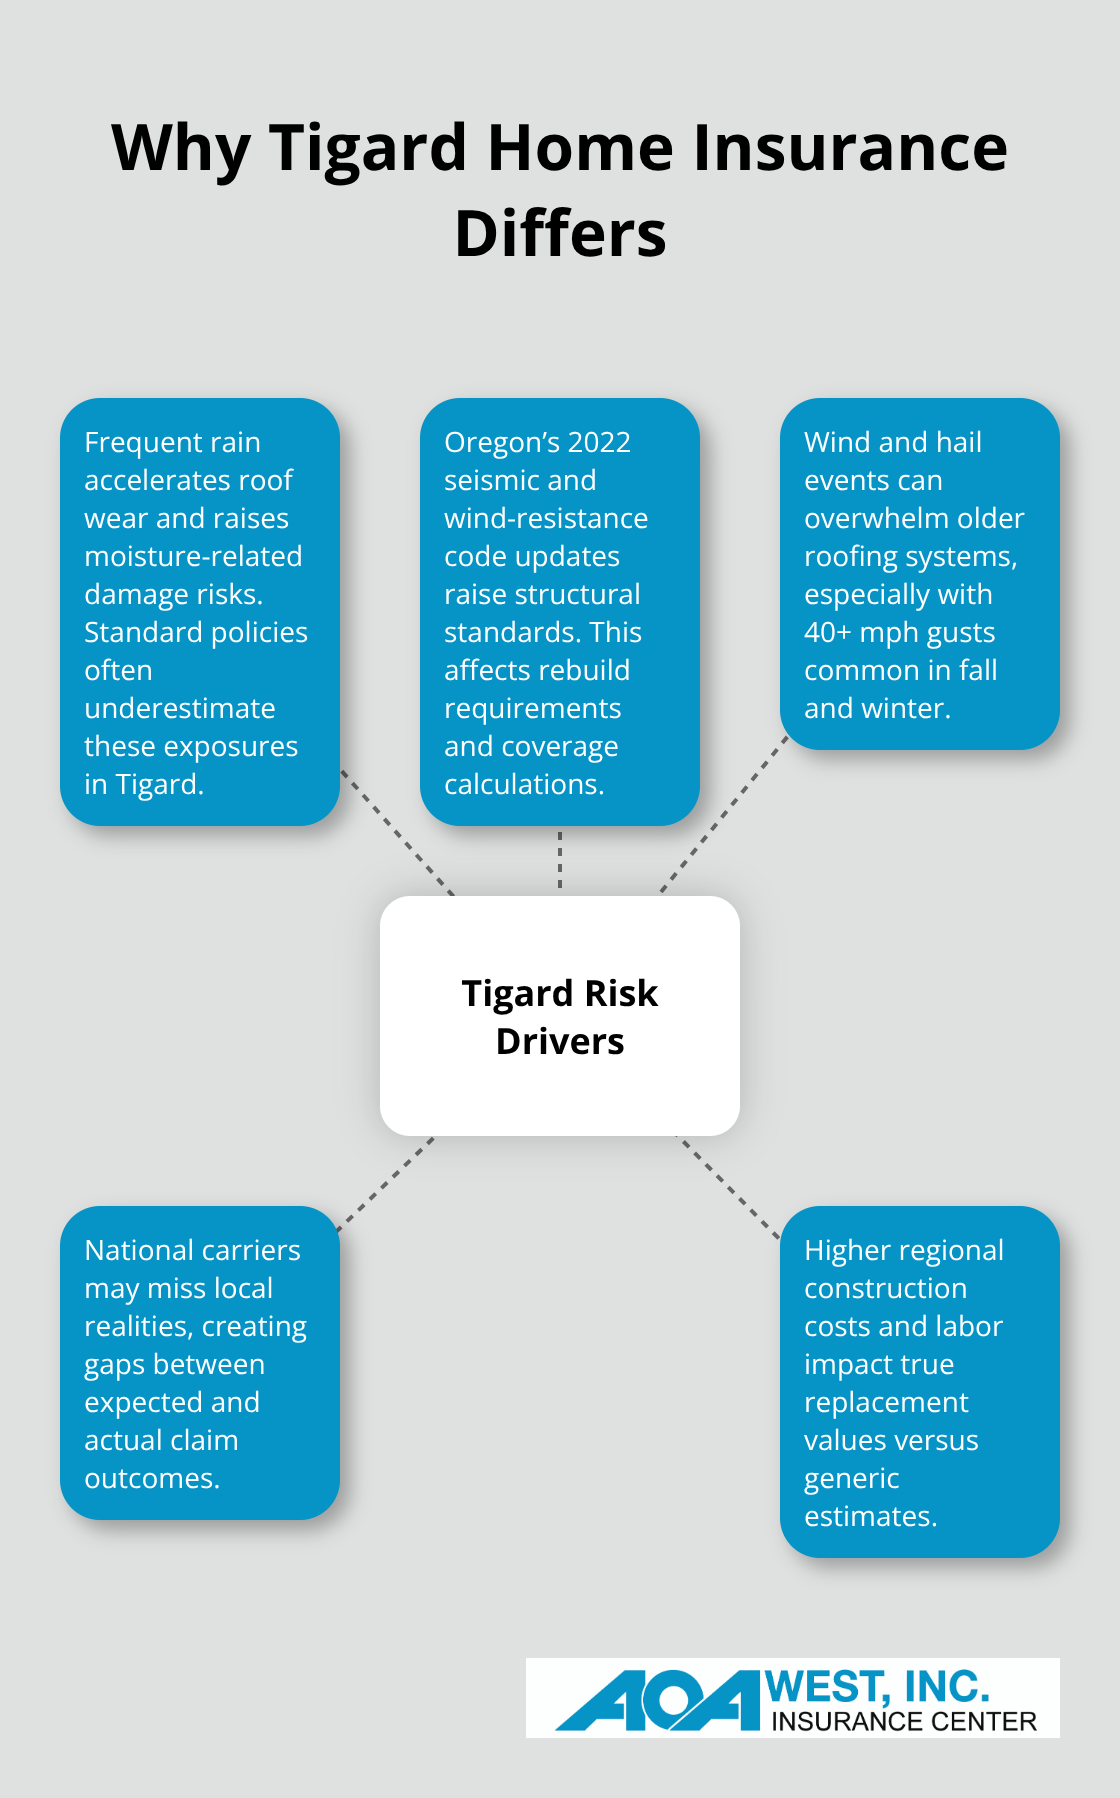
Tigard sits in a region where weather patterns and building regulations create insurance needs that differ significantly from most of the country. The Pacific Northwest experiences approximately 152 rainy days per year in the Tigard area, which accelerates wear on roofing materials and increases moisture-related damage risks that standard homeowners policies often underestimate. Oregon’s building codes, updated in 2022 to address seismic activity and wind resistance, require homes to meet specific structural standards that impact both replacement costs and coverage calculations. Many national insurers fail to account for these local realities, leaving homeowners with gaps between what they think is covered and what actually is when a claim occurs.
Climate-Specific Risks in Tigard
Tigard homeowners face three primary weather challenges that generic policies inadequately address. Heavy winter rains cause foundation seepage and basement flooding, which standard homeowners insurance typically excludes unless separate flood insurance is purchased through the National Flood Insurance Program. Hail events, while less frequent than rain, cause significant roof and siding damage; Oregon experienced notable hail storms in 2023 that led to thousands of claims across the state. Wind damage poses another serious threat, particularly for older homes with aging roofing systems that cannot withstand the 40+ mph gusts common during Oregon’s fall and winter storms.
Oregon Regulations That Affect Your Coverage
Oregon requires homeowners insurance to include replacement cost coverage for dwellings, not actual cash value, which is stricter than many states. This protects you but also means your policy limits must reflect current construction costs in Tigard, not outdated estimates. The Oregon Department of Consumer and Business Services mandates that insurers provide clear disclosure of coverage exclusions and limitations, so you can identify gaps before disaster strikes. Additionally, Oregon law allows insurers to require specific upgrades-like roof inspections or electrical system updates-before issuing policies on older homes, making it critical to understand these requirements upfront.
Local Market Knowledge Advantages
An agent familiar with Tigard’s insurance landscape knows which carriers offer competitive rates for homes in specific neighborhoods and which ones consistently undervalue properties in our area. AOA West, Inc., a family-owned independent agency serving Tigard since 1979, works with multiple carriers to compare how different insurers handle Tigard’s unique risks and find the combination of coverage and price that fits your actual situation. Local expertise also means understanding which homes qualify for discounts based on proximity to fire stations, water sources, and loss history in the area. These advantages matter most when you face a claim and need an agent who understands both your home’s specific vulnerabilities and the local claims process.
What Coverage Actually Protects Your Tigard Home
Understanding Your Dwelling Coverage Limits
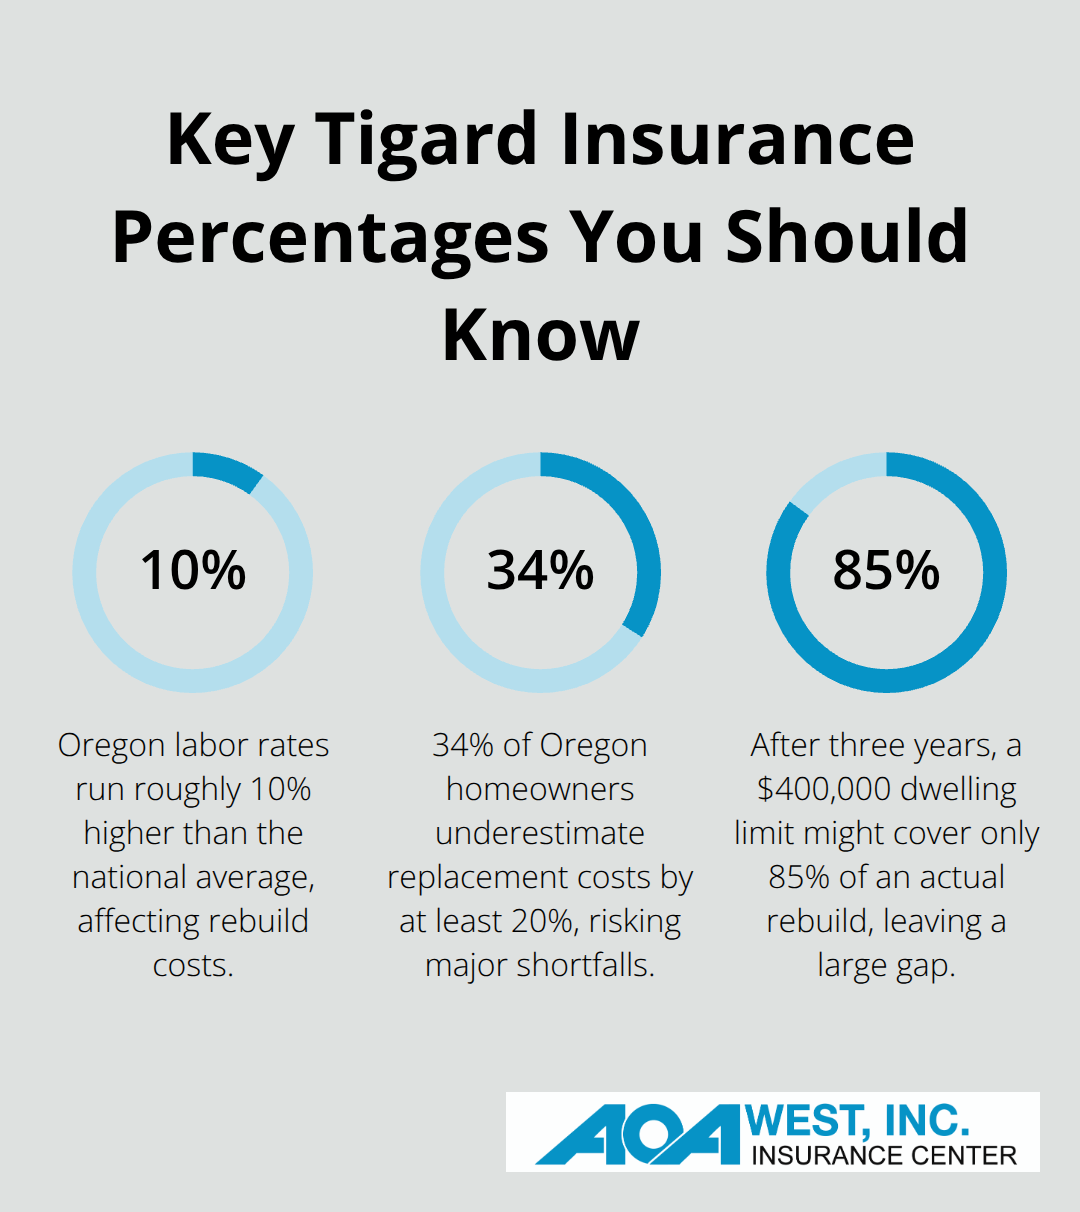
Standard homeowners insurance in Oregon covers dwelling damage, personal property, liability, and additional living expenses, but coverage limits matter far more than the policy name itself. Most Tigard homeowners purchase policies with dwelling coverage between $300,000 and $500,000, yet construction in Oregon costs more than the national average, with labor rates 10% higher, meaning a 2,500-square-foot home needs minimum coverage around $450,000 to $550,000 just for the structure. The Oregon Department of Consumer and Business Services found that 34% of Oregon homeowners underestimate their replacement costs by at least 20%, leaving them exposed to significant out-of-pocket expenses after a total loss.
Compare replacement cost estimates from at least two local contractors before you finalize your dwelling limit, since national insurers often use outdated square-footage calculations that don’t reflect Tigard’s actual construction market. This step takes a few hours but prevents thousands in uncovered losses.
Personal Property and Specialty Coverage
Personal property coverage typically caps at 50% to 70% of your dwelling limit, which proves inadequate for many Tigard households. If your home contains valuable collections, jewelry, or electronics, that standard coverage disappears quickly. Specialty coverage removes these limits entirely-jewelry endorsements eliminate the standard $2,500 cap, and silverware endorsements remove the $5,000 restriction that catches most homeowners off guard during claims.
High-value homes in Tigard’s established neighborhoods often require specialty policies because standard homeowners insurance simply wasn’t designed for significant asset protection. Work with an independent agent who can compare how different carriers handle valuables in your specific situation.
Weather-Specific Coverage for Tigard Risks
Flood damage, caused by the heavy rains that characterize our region, requires separate flood insurance through the National Flood Insurance Program; standard policies exclude it entirely, yet Tigard experiences localized flooding during heavy winter storms at least once every three to five years. Hail and wind damage coverage should include a deductible strategy that balances your monthly premium against realistic repair costs; many Tigard homes with older roofs face $8,000 to $15,000 in hail damage from a single storm, making a $1,000 deductible far more practical than a $2,500 option despite the slightly higher premium.
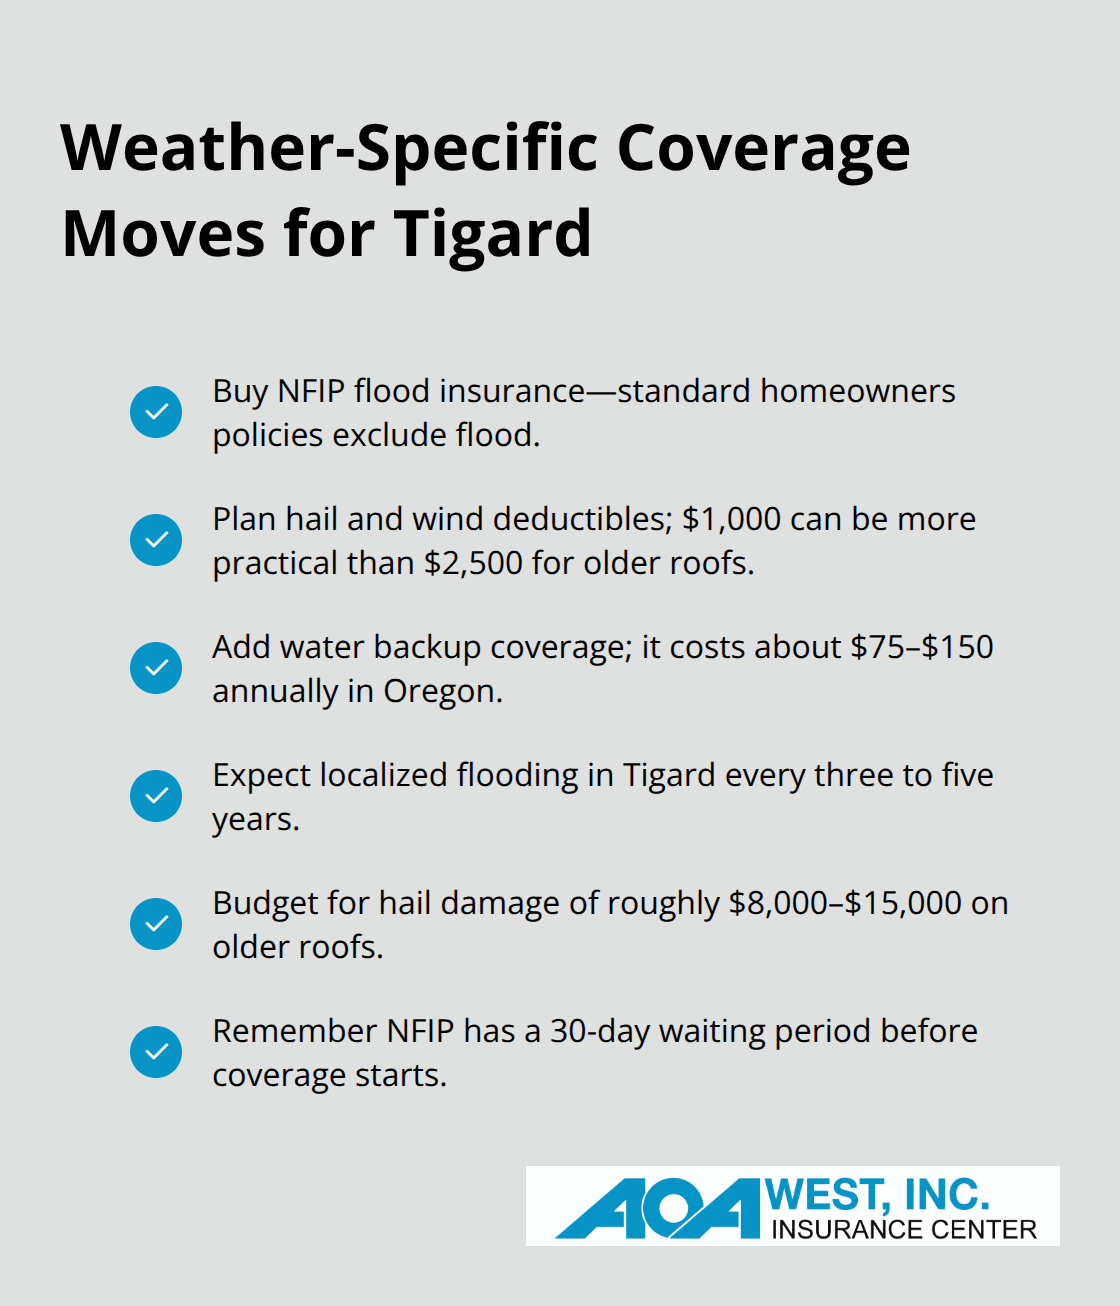
Water backup coverage protects against sump pump failures and sewage backups during heavy rains, costs between $75 and $150 annually in Oregon, and addresses a specific Tigard risk that catches most homeowners unprepared when their basement floods from internal plumbing failure rather than external flooding. This coverage often makes the difference between a manageable claim and a catastrophic loss.
Finding the Right Coverage Combination
The coverage you select today directly impacts what happens when a storm hits Tigard tomorrow. An independent agent working with multiple carriers can show you side-by-side comparisons of how different insurers handle our region’s specific weather threats and property values. This approach reveals which policies actually protect your home versus which ones leave expensive gaps that only appear after you file a claim.
What Tigard Homeowners Get Wrong About Insurance
Most Tigard homeowners catastrophically underestimate what their homes actually cost to rebuild. You might think your 2,500-square-foot home in a mid-range Tigard neighborhood needs $350,000 in coverage because that’s what you paid for it fifteen years ago, but Oregon construction costs have climbed significantly since then. Labor rates in Oregon run roughly 10% higher than the national average, and materials for homes built to current seismic and wind-resistance codes cost more than older construction methods. The Oregon Department of Consumer and Business Services reports that 34% of Oregon homeowners underestimate replacement costs by at least 20%, meaning they’d face massive out-of-pocket expenses after a total loss. This mistake isn’t minor-it’s the difference between recovering from disaster and losing everything your insurance was supposed to protect. Contact two local contractors in Tigard and ask what it would cost to rebuild your exact home from the ground up, then add 15% for inflation and code upgrades. That number, not your home’s market value, determines your actual dwelling coverage need.
Water Damage Blindspots in Tigard Homes
Tigard’s 152 annual rainy days create water damage scenarios that most homeowners don’t even know their policies exclude. Standard homeowners insurance does not cover flood damage from heavy rains, and the National Flood Insurance Program requires a 30-day waiting period before coverage becomes active, which means you cannot buy it after a storm watch is issued. Water backup coverage-protection against sump pump failures and sewage backups during heavy rain-costs only $75 to $150 annually in Oregon but stops thousands in basement damage that catches most Tigard residents completely unprepared. Many homeowners discover this gap only after their basement floods during the winter storms that hit our region every three to five years. Worse, some policies include water damage coverage that explicitly excludes water entering through foundation cracks or seepage, which is precisely what happens during Tigard’s heavy rains. Read your current policy and specifically search for what it says about foundation seepage, sump pump failure, and backed-up sewers, then talk to an independent agent about adding water backup coverage and understanding your flood insurance options immediately-not when rain is forecast.
The Annual Policy Review That Never Happens
Most Tigard homeowners sign up for insurance once and never look at their policy again until they file a claim, which is exactly when they discover their coverage has become inadequate. Your home’s replacement cost rises every year as construction materials and labor increase, yet your dwelling limit stays frozen at whatever you chose five years ago. Oregon requires insurers to provide renewal notices with clear coverage information, but these documents sit unread in most households. After three years, your $400,000 dwelling limit might protect only 85% of your home’s actual rebuild cost, leaving a $60,000 gap that comes straight out of your pocket.
Additionally, home improvements you’ve made-a new roof, updated electrical system, or added square footage-change your risk profile and might qualify you for discounts that your current policy doesn’t include. An independent agent can review your policy annually, compare your current coverage against updated replacement cost estimates, and identify whether rate increases reflect actual market changes or whether you should shop for better pricing with a different carrier. Try scheduling this review every October, before Tigard’s winter storm season, so your coverage reflects current reality instead of outdated assumptions.
Final Thoughts
The gap between what you think your Tigard Oregon home insurance covers and what it actually protects becomes painfully obvious only after disaster strikes. An independent agent who understands Tigard’s specific risks works differently than national call centers that process policies by the thousands without knowing your neighborhood’s weather patterns or local construction costs. We at AOA West, Inc. have spent nearly five decades helping Tigard homeowners build protection that matches their actual situation.
Working with multiple carriers means you see genuine side-by-side comparisons instead of whatever single option a captive agent can offer. When a winter storm floods your basement or hail damages your roof, you contact someone who knows exactly how your insurer handles Tigard claims and can advocate for you immediately, not someone reading from a script three states away. An independent agent also reviews your coverage annually as your home’s replacement cost climbs and your circumstances change, catching the gaps that most homeowners never notice until they file a claim.
The right insurance protects your home and your financial security. That protection starts with an agent who knows Tigard, understands Oregon’s specific requirements, and works with carriers that actually price fairly for our region’s real risks. AOA West, Inc. brings that local knowledge to every conversation, helping you choose coverage with confidence instead of hoping your policy covers what you think it does.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.