Getting the right insurance coverage isn’t something you should leave to chance. At AOA West, Inc., we work with Tigard residents to build personalized protection plans that actually fit their lives.
A local insurance agent in Tigard understands your community’s specific risks and can guide you toward coverage that makes sense for your situation. This guide walks you through what you need to know.
Why a Local Agent Matters in Tigard
Local Knowledge Shapes Better Coverage Decisions
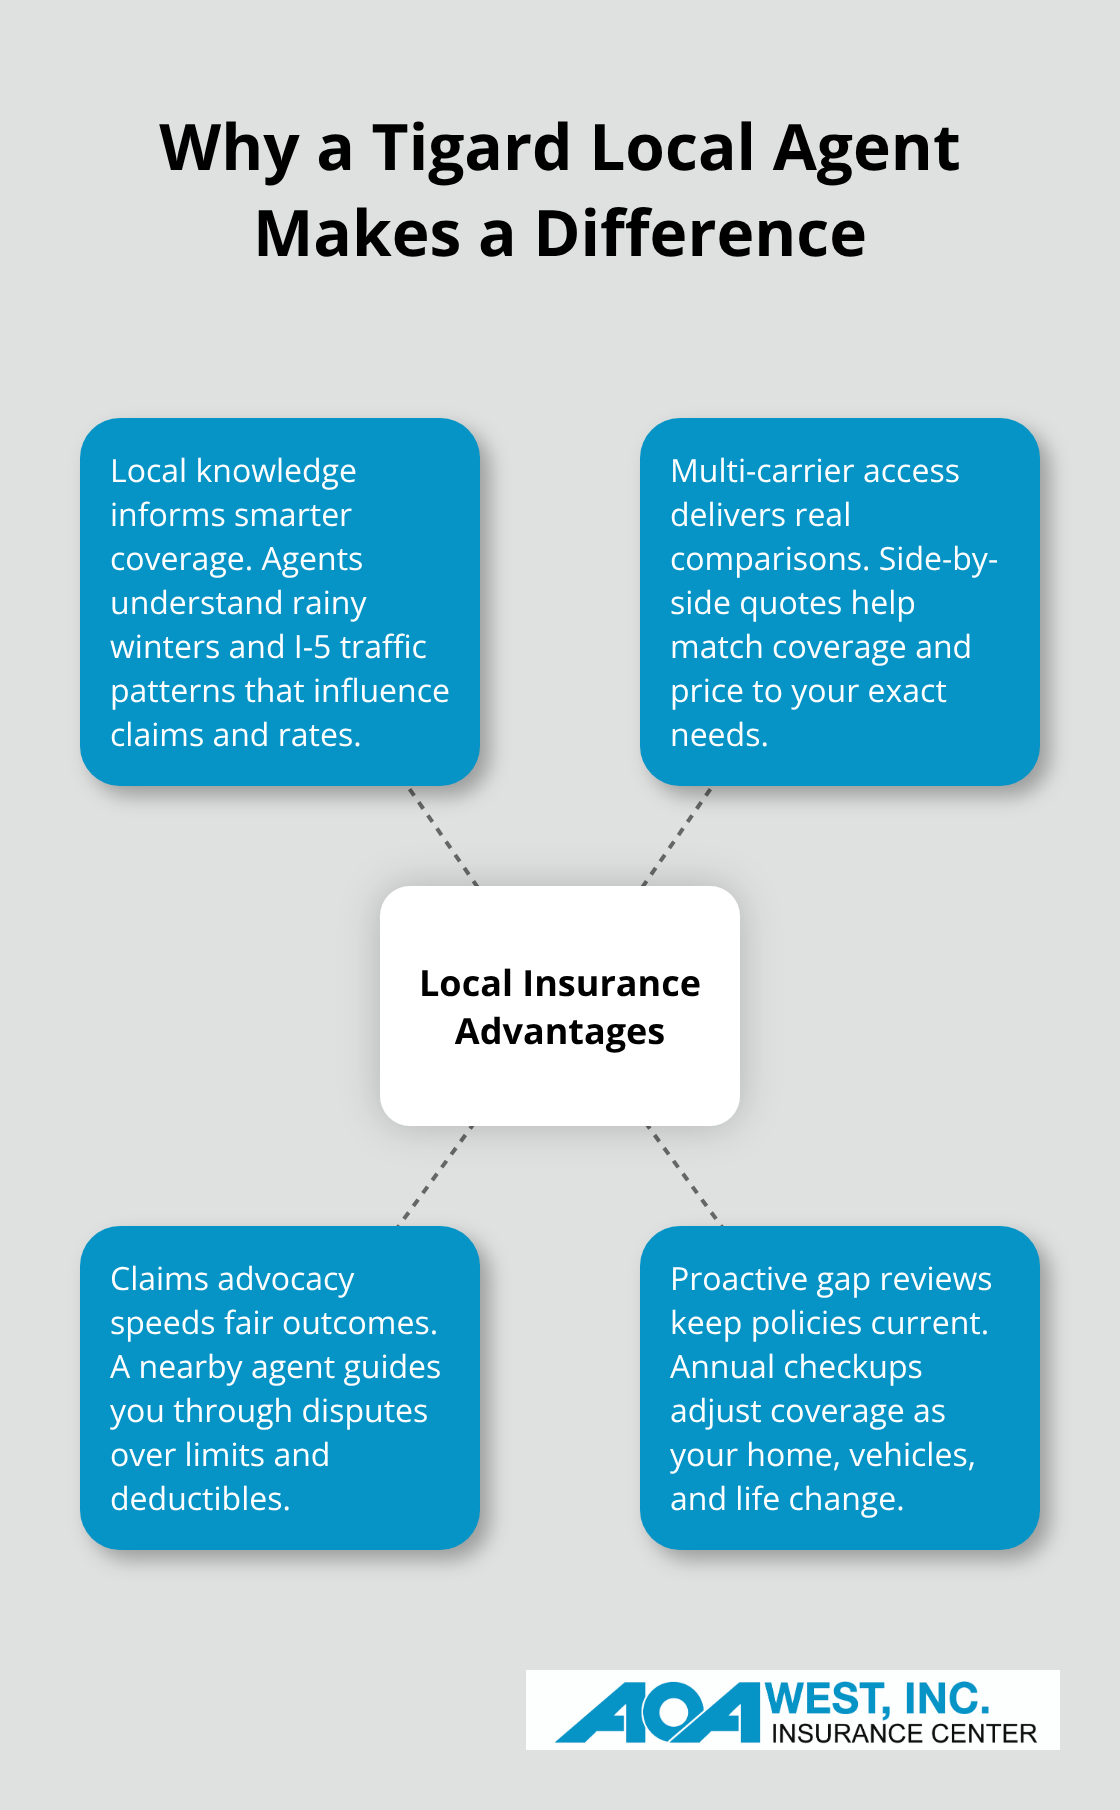
Shopping for insurance online or through a national call center leaves you vulnerable to gaps that matter. A local agent in Tigard understands the specific risks your community faces-from the rainy winters that trigger water damage claims to the I-5 traffic patterns that affect auto insurance rates. This knowledge helps you avoid the common mistake of accepting whatever coverage an insurer suggests without question. Instead, you receive guidance tailored to your actual situation, whether that involves protecting a newly renovated home or covering a collector vehicle that needs specialized insurance.
Multiple Carriers Mean Real Comparison Power
One company’s online quote locks you into that carrier’s offerings. A local independent agent works with multiple carriers, which means you see concrete side-by-side comparisons of coverage options and prices. This access to different providers prevents you from settling for limited choices. At AOA West, Inc., we work with multiple carriers to deliver personalized guidance and clear comparisons so you can choose tailored protection with confidence.
You gain the power to select coverage that actually fits your needs rather than accepting whatever a single insurer recommends.
Claims Support When It Matters Most
Filing a claim through a distant representative who knows nothing about Tigard creates unnecessary friction. A local agent advocates for you during the claims process and understands how local circumstances affect your coverage. Claims often involve disputes about coverage limits or deductibles, and having an agent who knows your policy details and your community makes a real difference in how quickly and fairly your claim gets resolved.
Proactive Gap Identification Protects Your Future
A good local agent reviews your coverage annually to catch gaps before they become expensive problems. Many Tigard residents discover they’re underinsured only after a loss occurs-far too late to adjust. A proactive agent identifies these gaps (insufficient liability limits, missing specialty coverage for valuables, or inadequate protection for high-value items) while you still have time to strengthen your policies. This ongoing relationship means your coverage evolves as your life changes, rather than remaining static year after year.
What Coverage Types Protect Your Tigard Home and Vehicles
Home Insurance Addresses Oregon’s Water Damage Realities
Home insurance in Oregon requires specific attention to water damage and weather-related claims. Standard homeowners policies in Tigard typically cover fire, theft, and wind damage, but many residents misunderstand what happens during the heavy rain seasons that define our region. According to the National Association of Insurance Commissioners, water damage from poor drainage or foundation issues falls outside standard coverage and requires separate endorsements. This gap costs Oregon homeowners thousands annually.
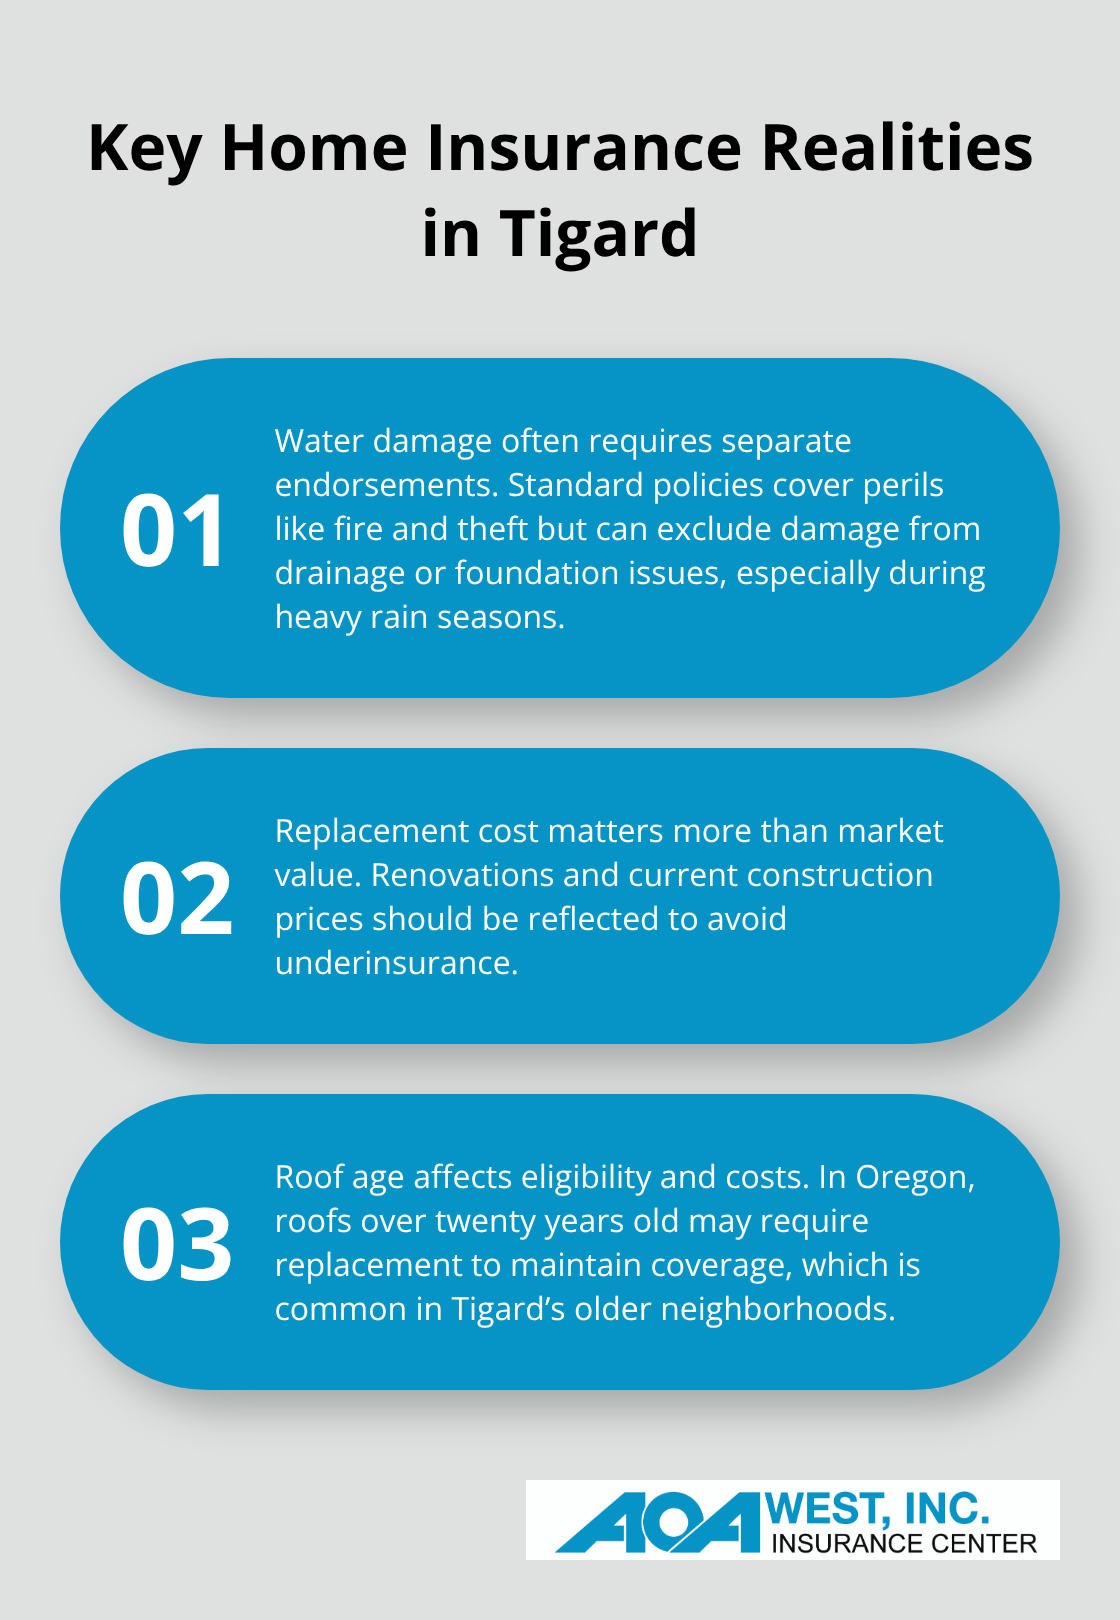
Your home’s replacement cost matters more than its market value. If your 1,500-square-foot house sits on valuable land, the replacement cost of rebuilding that structure alone determines your coverage limit, not what you could sell the property for. Establishing accurate replacement cost estimates that reflect current construction prices (rather than outdated assessments) protects you from underinsurance. Additionally, if you’ve made significant renovations, your existing policy likely undervalues those improvements.
Roof age also affects coverage significantly. Most insurers in Oregon require roof replacement if it exceeds twenty years, and this becomes a real issue in Tigard where older homes dominate neighborhoods.
Auto Insurance Complexity Increases with Specialty Vehicles
Auto insurance for Tigard drivers involves more complexity than most people realize, particularly for those with classic or collector vehicles. Standard auto policies don’t cover vintage cars adequately because they use actual cash value calculations that depreciate collector cars to near-zero within years, despite their true market value increasing. Collector car insurance operates differently-it recognizes that a 1967 Mustang or 1985 Ferrari appreciates over time and covers replacement value instead of depreciation.
If you own multiple vehicles or specialty cars, your standard homeowners and auto policies likely leave gaps in coverage. Specialty vehicle insurance addresses motorcycles, ATVs, RVs, and high-performance cars that fall outside conventional policies. Oregon’s I-5 corridor creates specific auto insurance considerations, and uninsured motorist coverage becomes essential protection given Oregon’s higher uninsured driver rates.
These coverage gaps demand attention before a loss occurs, which is why understanding what your current policies actually protect matters far more than most Tigard residents realize.
Coverage Gaps That Cost Tigard Homeowners and Drivers Real Money
Underinsurance Leaves You Exposed to Catastrophic Loss
Most Tigard residents face their insurance gaps only after a loss occurs, which means they’re already out of pocket thousands of dollars. Underinsurance represents the most common and expensive mistake people make.
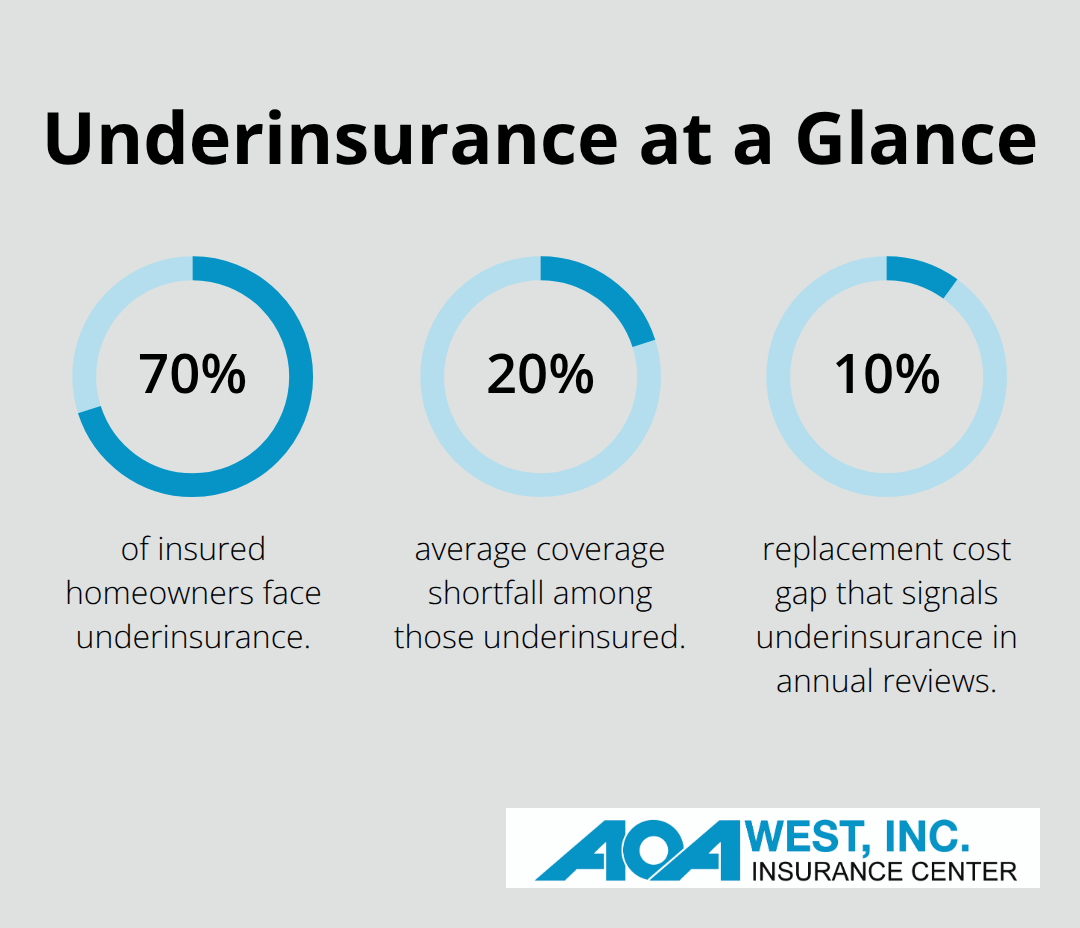
Over 70% of insured homeowners face average 20% shortfalls, and this problem worsens in Oregon where construction costs have risen significantly. Your policy limit should reflect the actual cost to rebuild your home from the foundation up, not what you paid for the property twenty years ago. A contractor in Tigard today charges roughly $150 to $200 per square foot for residential construction, which means a 2,000-square-foot home requires coverage between $300,000 and $400,000 just for the structure itself. If your policy tops out at $250,000, you’ll cover only the foundation and framing when a total loss occurs.
The same problem affects auto insurance-drivers often carry liability limits of 25/50, which means $25,000 per person and $50,000 per accident. A single serious injury claim in Oregon regularly exceeds $100,000, leaving you personally liable for the difference. This gap exposes your personal assets to seizure if a court judgment exceeds your policy limits.
Specialty Coverage Gaps Hide in Plain Sight
Valuable items including jewelry, art, collectibles, and electronics receive only limited coverage under standard policies-typically $1,500 to $2,500 total for all valuables combined. A single piece of jewelry or a collection of vintage watches can exceed this limit without any additional endorsement. Collector vehicles, motorcycles, or RVs need separate specialty policies rather than standard endorsements, yet most Tigard residents treat these as afterthoughts rather than priorities.
Standard homeowners policies simply don’t account for the true value of what you own. A wine collection, photography equipment, or high-end electronics all fall into coverage gaps that leave you unprotected. Requesting an inventory of items covered under your homeowners policy’s personal property section helps you identify anything that exceeds the standard limit.
Deductible Choices Create Financial Strain
Deductibles create another hidden gap that catches people off guard. Selecting a $1,000 deductible instead of $500 saves money on premiums, but it means you’ll pay that full amount out of pocket for every claim, regardless of size. Many Tigard residents select high deductibles during good years, then face financial strain when they need to file a claim for water damage or a minor auto accident.
Your deductible selection should reflect what you can actually afford to pay out of pocket, not just what saves money on premiums. A $500 deductible might cost $50 more annually, but that protection matters when a water damage claim hits your foundation or a fender-bender requires repairs.
Oregon’s Specific Risks Demand Tailored Coverage
Oregon’s wet climate triggers foundation and water damage claims that standard policies often exclude or severely limit. Water damage represents one of the fastest-growing homeowners insurance claims in the Pacific Northwest. Heavy traffic on I-5 creates specific auto insurance considerations, and uninsured motorist coverage becomes essential protection given Oregon’s higher uninsured driver rates compared to national averages.
Coverage choices that account for your actual location and driving patterns protect you far better than generic national policies. Verify that your liability limits exceed $100,000 per person, particularly if you own assets worth protecting. Compare your home’s replacement cost estimate against your policy limit annually-if the gap exceeds 10 percent, you’re underinsured and vulnerable.
Final Thoughts
Finding the right local insurance agent in Tigard requires looking beyond price quotes. Experience matters significantly-agents who’ve worked in the Tigard market for years understand the specific coverage gaps that catch residents off guard. Ask potential agents about their credentials, whether they hold designations like Certified Insurance Counselor (CIC) or Chartered Property Casualty Underwriter (CPCU), and how long they’ve served the community.
When comparing agents, request quotes from multiple carriers side-by-side rather than accepting single-company estimates. A local insurance agent in Tigard will show you how different carriers price the same coverage and explain why those differences exist. This transparency lets you make informed decisions based on actual numbers rather than marketing claims.
Your coverage needs change when you renovate your home, purchase a collector vehicle, or experience life shifts like retirement. An agent who reviews your policies annually catches gaps before losses occur and adjusts your protection as your situation evolves. Contact AOA West, Inc. to discuss your coverage needs with agents who understand the specific risks your community faces.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.