Condo owners in Oregon face insurance decisions that differ significantly from single-family homeowners. Getting accurate Oregon condo insurance quotes requires understanding what coverage actually protects your property and what gaps might leave you exposed.
At AOA West, Inc., we help Tigard-area condo owners compare quotes effectively and find the right protection for their specific situation. This guide walks you through the comparison process so you can make a confident decision.
Why Oregon Condo Coverage Differs from Other Properties
State Requirements and Master Policy Gaps
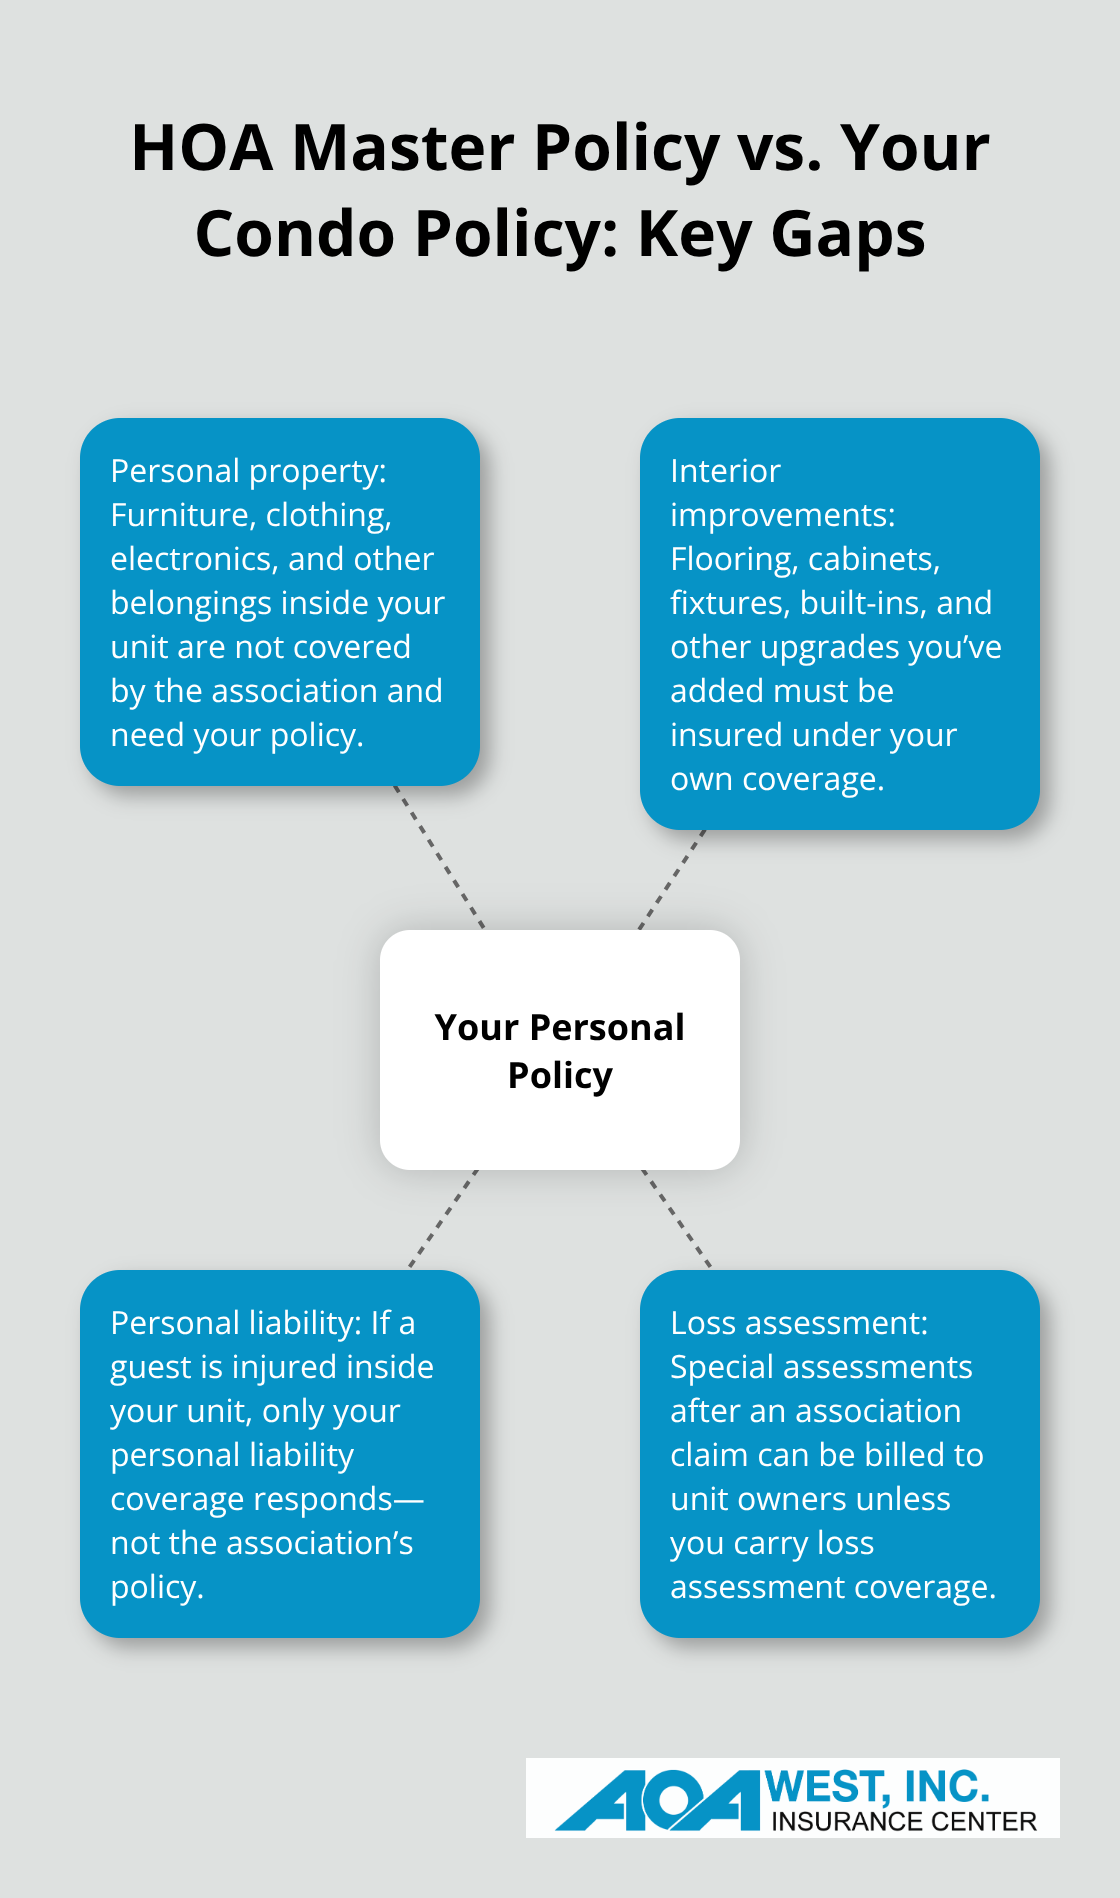
Oregon Revised Statutes Chapter 100 requires condo associations to maintain master insurance policies covering the building structure, but these policies contain significant gaps that individual unit owners must fill with their own coverage. The state doesn’t mandate specific condo insurance minimums for owners, which means many Tigard-area residents purchase inadequate policies without realizing what they’re missing. Your condo association’s master policy typically covers the building’s exterior walls, common areas, and shared systems, but it won’t protect your personal belongings, interior improvements you’ve made, or your liability if someone gets injured inside your unit.
Portland Metro Risks That Standard Policies Overlook
Portland metro condo complexes face particular risks that standard policies often overlook: older buildings with outdated electrical systems, shared walls that transmit fire quickly between units, and dense construction that complicates water damage claims. Water damage represents a significant category of condo insurance claims, yet many owners don’t realize their association’s policy excludes coverage for damage originating from their individual unit. Earthquake risk presents another serious consideration in the Portland area, where the Cascadia Subduction Zone poses genuine threat potential, and most standard condo policies exclude seismic damage entirely unless you add specific earthquake endorsements.
The Coverage Confusion That Costs Owners Money
The most common mistake condo owners make involves confusing their association’s coverage with personal protection. Many assume their condo association’s master policy protects everything, leading them to purchase minimal personal coverage when they should be protecting their actual exposure. Oregon’s consumer complaint data shows that claim disputes over coverage responsibility between owners and associations rank among the top sources of insurance litigation in the state.
Your individual policy must cover interior walls, flooring, cabinets, appliances you’ve installed, and personal property inside your unit, but you need to verify exactly what your association’s policy covers before deciding on your own limits. Liability coverage gaps create another serious exposure: if someone slips in your unit and sues, your personal liability limit becomes critical, and the association’s policy won’t protect you individually.
Taking Action Before You Compare Quotes
Request a copy of your condo association’s master insurance policy and declarations page before requesting quotes, so you know precisely what protection already exists and what you need to purchase. This step transforms your quote comparison from guesswork into an informed process where you can accurately evaluate what each carrier actually offers for your specific situation.
How to Compare Condo Insurance Quotes Effectively
Normalize Your Quotes to Reveal Real Price Differences
When you place three Oregon condo insurance quotes side by side, premium differences can vary significantly across carriers. Carriers weight risk factors differently, and most condo owners lack a structured method to confirm they’re actually comparing the same protection across quotes. Start by requesting quotes using the exact same deductible amount-typically $500 or $1,000-across all three carriers, then note which coverage limits each quote includes for personal property, liability, and loss assessment protection.
Personal property coverage limits vary dramatically: one carrier might quote $15,000 while another offers $25,000 at nearly the same price, which means you’re not seeing an apples-to-apples comparison until you normalize this variable. Ask each carrier to spell out their specific limits for water damage, earthquake coverage, and loss assessment liability, since these categories hide the most significant cost drivers and protection gaps that trip up Tigard-area owners during claims.
Identify Red Flags That Signal Inadequate Quotes
Three specific red flags separate problematic quotes from solid ones. First, a carrier quotes you without asking detailed questions about your unit’s interior modifications, square footage, or proximity to other units-this suggests they’re using templates rather than actual risk assessment. Second, watch for quotes that bundle earthquake coverage into the standard policy without separating the cost, which makes it impossible to evaluate whether the premium reflects genuine seismic protection or just marketing language.
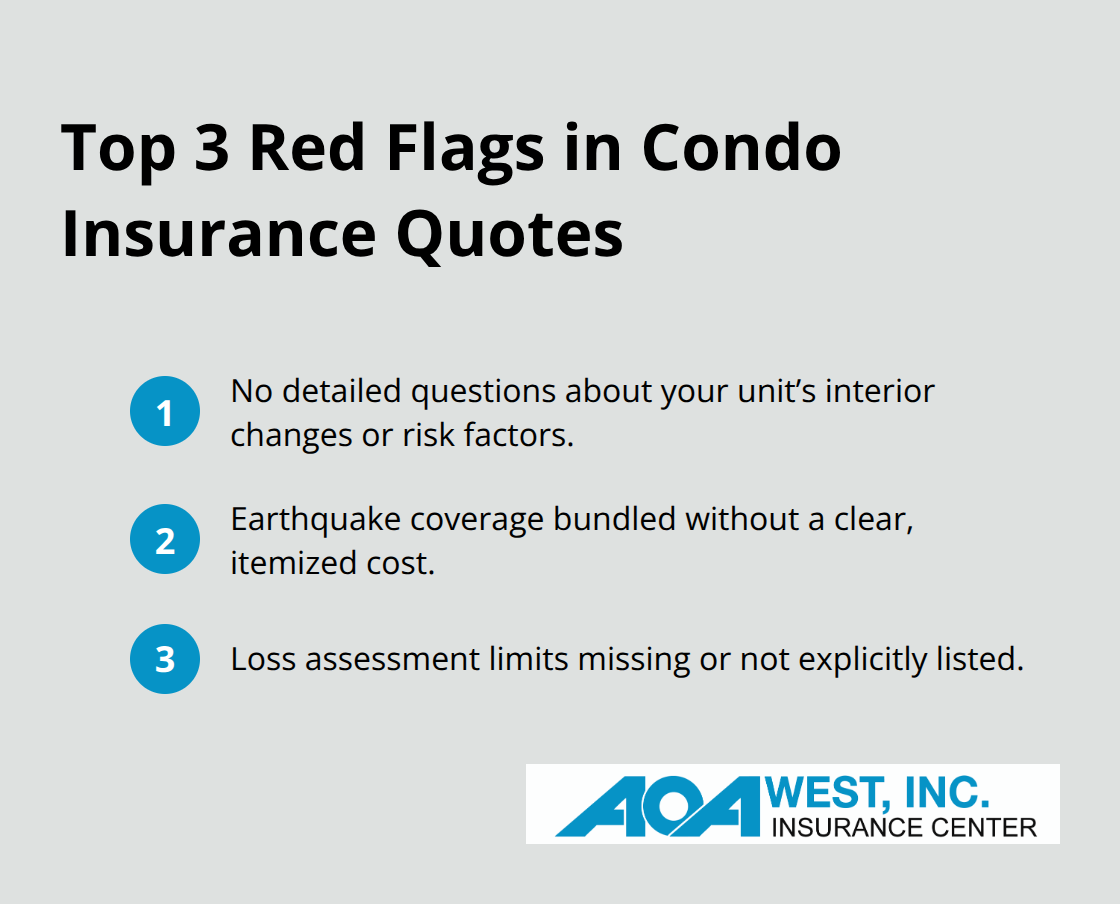
Third, any quote that doesn’t explicitly list loss assessment coverage limits (the amount protecting you if the association’s insurance proves insufficient) should raise immediate concern. Oregon condo owners face genuine exposure here, and carriers who gloss over this coverage are cutting corners on your protection.
Create a Specification Sheet for Accurate Comparisons
A detailed specification sheet that lists every coverage type, limit, and deductible transforms quote comparison from a frustrating guessing game into a concrete decision-making process. Make sure every quote offers the same coverage, limits, and deductibles (or as close as possible), so you can confidently choose the lower premium. This approach eliminates confusion and reveals exactly where price differences come from.
Working with a local independent agent who represents multiple carriers gives you access to this structured comparison approach without doing the legwork yourself. An agent can request quotes using standardized specifications and present them side by side, showing you precisely how coverage and cost differ across carriers for your specific Tigard condo situation.
Getting Accurate Quotes Fast in Oregon
Prepare Your Condo Details Before Requesting Quotes
Accurate Oregon condo insurance quotes arrive faster when you compile specific information beforehand. Carriers need the year your building was constructed, your unit’s square footage, number of bedrooms and bathrooms, distance to the nearest fire station, whether your building has sprinkler systems, and a complete list of interior upgrades like new flooring, kitchen renovations, or updated electrical work. Vague requests delay responses by days, while detailed information moves quotes through underwriting quickly. You’ll also need your condo association’s master policy declarations page, which shows exactly what coverage already exists, and your association’s contact information so agents can verify coverage details directly. Most Oregon carriers ask about your claims history, credit score factors, and whether you occupy the unit year-round or seasonally, so have this information ready to accelerate the quoting process.
Compare Online Platforms Against Local Agent Approaches
Online quote platforms like Insurify or The Zebra promise quick estimates but typically deliver generic numbers that don’t account for Oregon-specific risks or condo-specific exposure. These platforms funnel your information to multiple carriers simultaneously, which creates volume but sacrifices accuracy for your particular situation. Local independent agents who represent multiple carriers offer a significant advantage: they understand Portland metro construction patterns, know which carriers price competitively for Tigard condos, and request quotes using standardized specifications so you receive genuine apples-to-apples comparisons. An agent handles the legwork of gathering your condo details, contacting carriers, and organizing quotes into a clear side-by-side format, which typically takes three to five business days once you provide your information.
Understand the Real Timeline for Final Quotes
Online platforms often deliver initial estimates within hours, but these preliminary numbers frequently change once carriers perform detailed underwriting, making the speed advantage meaningless. The real timeline that matters is how long until you hold final, bindable quotes you can actually act on. That process typically ranges from five to seven business days regardless of your approach (online or agent-assisted).
Expect to spend 30 to 45 minutes providing detailed information to your agent, then allow three to five business days for carriers to respond with formal quotes. This structured timeline helps you plan your decision-making process without false expectations about speed.
Work with Agents Who Specialize in Condo Coverage
Independent agents in the Tigard area who focus on condo insurance understand the specific gaps that trip up Oregon owners. These agents present multiple quotes with identical coverage specifications so premium differences reflect actual carrier pricing rather than coverage variations. They ask the right questions about your unit’s unique features and your association’s master policy, which online platforms cannot replicate. This personalized approach transforms quote comparison from a frustrating guessing game into a concrete decision-making process where you can confidently choose based on price and service quality.
Final Thoughts
Comparing Oregon condo insurance quotes effectively requires three concrete actions: normalize your quotes using identical coverage specifications, gather detailed information about your unit before requesting quotes, and accept that accurate comparisons take five to seven business days regardless of your approach. Premium differences across carriers often reflect genuine pricing variations rather than coverage gaps, but only when you compare the same protection across all quotes. Skip this normalization step and you’ll chase misleading price differences that vanish once you account for coverage variations.
Request a copy of your condo association’s master policy declarations page and compile your unit’s specific details (construction year, square footage, upgrades, distance to fire station). Contact multiple carriers using these standardized specifications so you eliminate guesswork and reveal exactly where price differences originate. This approach shows you which carriers price competitively for Tigard condos while others don’t, and only a structured comparison exposes this reality.
We at AOA West, Inc. work with multiple carriers to deliver side-by-side comparisons of Oregon condo insurance quotes using identical specifications, so you can choose based on price and service quality rather than confusion. Our team understands Portland metro construction patterns and knows which carriers handle condo claims fairly. Contact us to receive quotes that reflect your actual protection needs and your unit’s specific risk profile.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.